PHASE 01What happened?
Descriptive
We rebuild the statements and the real cash flow, with no accounting make-up. Before forming an opinion, we verify the information is admissible.
Twenty-five years rebuilding the mechanism that generates value in real companies —ROIC, WACC, cash, risk— with a four-phase method that stays installed inside, running without us.
Each service opens its own page with a different simulator, fully in English: try your own numbers before writing to us.
Deal structuring, counterparty search and negotiation for sales, mergers and joint ventures — with the valuation settled before sitting at the table.
DCF, multiples and scenario valuations, with an emerging-market risk premium and illiquidity discounts that are calculated, not eyeballed.
Debt reprofiling, working-capital optimisation and profitability recovery plans with quarterly targets.
Predictive models and Monte Carlo simulations that anticipate cash flow, risk and sensitivities, connected to your ERP through an MCP.
Financial and risk review accelerated by automated document reading: from weeks to days, without losing depth.
Budgets, forecasts and control dashboards tied to the business's real drivers, with quarterly plan-vs-actual reviews.
Redesign of administrative processes and financial controls so information arrives on time, error-free and without individual heroics.
Permanent financial follow-up: a weekly meeting with that week's analysis and, at month-end, a summary with conclusions and prescriptions.
Four questions, in order, about the same number. That passage —from loose data to free cash flow— is literally our job.
We rebuild the statements and the real cash flow, with no accounting make-up. Before forming an opinion, we verify the information is admissible.
Five-factor DuPont, cash conversion cycle, ROIC−WACC spread and Altman Z′′ for emerging markets. Every point of EVA attributed to its driver.
Monte Carlo with 10,000 iterations that runs through the adjusted model, not around it. P10 / P50 / P90 percentiles and CFaR instead of adjectives.
Levers ranked by value impact and implementation effort. What we install keeps running in your company, without us.
A company can grow, sell more and still destroy value. There is only one condition: the return on invested capital must exceed what that capital costs.
78% of the debt matured within 180 days. We reprofiled with four banks and redesigned working capital before touching the cost structure.
USD DCF with its own country-risk premium —no double counting on Ke— and an illiquidity discount calculated, not eyeballed.
Monte Carlo across 10,000 scenarios: only 34% justified the premium. We restructured the offer with an earn-out tied to verified EBITDA.
ROIC of 9.1% against a WACC of 12.4%. We redesigned the D/V mix and stopped two lines that did not cover their cost of capital.
MCP on the ERP and an ABC/XYZ matrix by SKU: 8% of the codes tied up 41% of working capital. The dashboard keeps running without us.
Nearly 25 years of practice with real Argentine SMEs. MSc in Corporate Finance and in Business Intelligence. The four-phase method we structure every mandate with is his.
LinkedIn ↗
More than 25 years leading Administration and Finance in corporate holdings and SMEs. Former Administration and Finance Manager in Argentina for multinational infrastructure and civil engineering groups. Leads accounting governance, data integrity and deliverable quality control at JPR Consulting.

Business valuation and financial planning specialist, with his own work in algorithmic trading and quantitative models. Where one looks at the internal mechanism of value, the other looks at the price the market will put on it.
LinkedIn ↗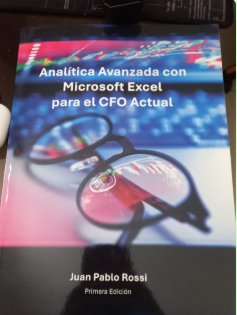
Dynamic arrays, Monte Carlo and neural networks inside Excel. Not a single line of VBA. Published in Spanish.
We publish the frameworks we use and the simulators running behind them. If you cannot audit how we got to the number, it is useless.
What we install keeps running in your company even if we stop working together. We do not sell subscriptions disguised as consulting.
A family business of twenty employees and a group of four hundred are not analysed with the same template.
The person who does the analysis is the one who presents it. No intermediate layers, no deliverables written by someone who never saw your operation.
Compará ahorro, costo del inventario y capacidad de pagar el pedido. Caso hipotético con sensibilidad interactiva.
→Caso práctico: anticipos, plazos y financiamiento antes de aceptar un contrato. Serie Decisiones que crean valor, entrega 1.
→Cómo cuantificar con Monte Carlo el sobrepago en adquisiciones, integrando iliquidez, riesgo país y opciones reales.
→Cómo la proporción exacta de deuda y capital propio determina cuánto vale una empresa, según McKinsey.
→Por qué crecer en el mercado equivocado destruye valor, y cómo descomponer el crecimiento en tres vectores.
→Tell us the decision, deadline and your role. If there is a fit, we arrange a free 30-minute exploratory conversation. A valuation or a definitive diagnosis requires sufficient information and an agreed scope.
With growing SMEs, mid-sized family businesses and family offices. The scope adapts to size and stage: we do not apply the same mould to a company of 20 and one of 400 employees.
Three measurable things: predictive cash-flow models, Monte Carlo with 10,000 iterations to quantify risk, and an MCP connected to your ERP so you can ask your own data questions. None of it replaces judgement: it accelerates it.
No. What we install keeps running in your company even if we stop working together. It is an explicit decision of our working model: we do not sell dependency.
Yes. It is a 30-minute exploratory conversation to understand the decision, timing and available information. It does not include a valuation or a definitive diagnosis without sufficient evidence.
Yes. The models are adapted to both markets: inflation and AXI adjustment in Argentina, dollarisation and a dedicated country-risk premium in Ecuador, without double counting risk.